

Consumer credit in Benin: required documents, how it works, and why the informal sector remains largely excluded ?
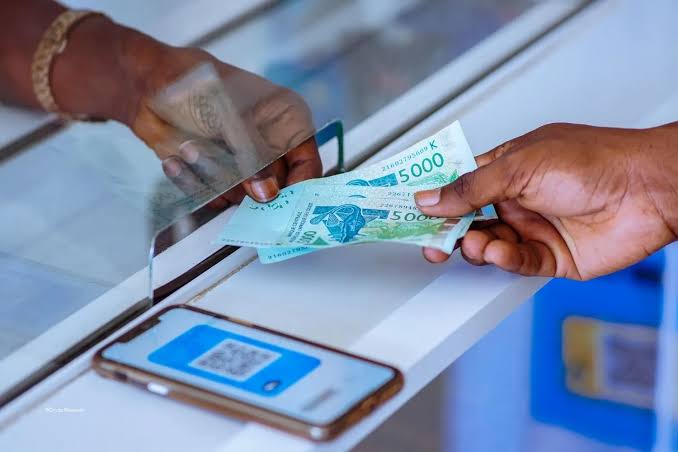
Consumer credit in Benin: a product tailored for the formal sector
Consumer credit, along with auto loans and mortgage loans, is one of the most sought-after products in Beninese banks. It finances the purchase of equipment, a wedding, school fees, an emergency, or simply a temporary cash need. Unlike mortgage loans, it requires neither a mortgage nor a land title, which in theory makes it more accessible. But in practice, it is built around a specific profile: the formal-sector employee with an indefinite-term contract (CDI), whose income is verifiable and can be domiciled. This article details the typical journey of a consumer credit application, illustrated by the documents actually required for a permanent employee, and then analyzes why this same process remains structurally very difficult for those in the informal economy, who nevertheless represent the majority of Benin's active population.
1. What is consumer credit?
Consumer credit is a medium-term loan, either unallocated or allocated to a specific use (purchase of equipment, vehicle, financing a family event). It differs from mortgage loans in that it does not require a mortgage guarantee and has much shorter terms. It relies above all on the borrower's regular repayment capacity, generally demonstrated by a domiciled salary.
2. The standard application: documents required for a formal-sector employee
Based on practices observed in local banks, a consumer credit application for a permanent employee typically includes the following categories of documents:
2.1. Identity and civil status
- Valid identity document: national identity card or CEDEAO biometric identity card;
- Client confidential information form: an internal form filled out with the applicant, which records civil status, family situation, number of dependents, full address, and often a declaration of assets (real estate, vehicles, other assets) and existing financial charges (existing loans, mortgage charges). This document serves as the basis for the overall solvency analysis, beyond just salary income.
2.2. Employment and income proof
- Employment contract (ideally permanent) or, failing that, a minimum seniority in a fixed-term contract;
- Certificate of employment issued by the employer, specifying the position held and the start date;
- Recent pay slips (generally the last three months), which detail base salary, allowances (transport, housing, responsibility), social security contributions (CNSS), and the net amount payable.
2.3. Irrevocable salary domiciliation
This is the central piece of the arrangement: an irrevocable domiciliation letter, sent by the employer (or the payroll management structure) to the employee's bank, committing to pay all remuneration into the account opened with that bank, with no possibility of revocation without the written consent of both the employee and the bank. This domiciliation constitutes, in fact, the main guarantee of consumer credit: it gives the bank direct and continuous visibility over the borrower's income, allowing it to deduct the monthly installment before any other use of the salary.
2.4. Summary of documents usually required
- Identity: Valid national identity card or CEDEAO card
- Personal situation: Confidential information form (civil status, charges, assets)
- Employment: Employment contract, certificate of employment from employer
- Income: Last 3 pay slips
- Guarantee: Irrevocable salary domiciliation (employer letter + employee letter + RIB)
- Bank account: Bank account details (RIB)
Depending on the amount requested and the institution's policy, other documents may be required: recent proof of address (electricity or water bill), tax identification document (IFU), recent bank statements, or, for an allocated loan (vehicle purchase, renovations), a pro forma invoice or quote justifying the use of funds.
3. Approval conditions: what weighs in the decision
- The assignable portion: the monthly installment, added to those of any existing loans, generally cannot exceed a ceiling percentage of net salary (commonly around 33 to 40%);
- Contractual status: several personal loan offers explicitly require a permanent contract, as well as a maximum age at loan maturity (often around 60 years);
- Duration: consumer loans most often extend over 12 to 60 months, with some personal loan offers reaching up to 80-83 months depending on the amount and profile;
- Loan-related insurance: death-disability, sometimes unemployment, compulsory in almost all offers;
- The effective annual rate (APR): it includes the nominal rate, application fees, and insurance premiums — it is this, not the advertised rate, that reflects the true cost of credit.
4. Specific complications for informal sector profiles
The informal economy represents, according to available estimates, nearly 80% of Beninese economic activity — traders, artisans, transporters, farmers, service providers. Yet the very structure of the consumer credit described above relies on elements that this public cannot, by definition, produce.
4.1. No employment contract or pay slip
Without a formal employer, there is no employment contract, no certificate of employment, and no regular monthly pay slip. Yet these three documents form the foundation on which a bank assesses income stability and recurrence. A trader or artisan, even with a solid turnover, cannot produce the direct equivalent of these documents.
4.2. The impossibility of domiciling a salary that does not exist
The central guarantee of classic consumer credit — irrevocable salary domiciliation — simply has no equivalent for self-employed income, whose receipts are irregular, in cash or via mobile money, and spread across multiple channels. Banks, which structure their product around this guarantee, find themselves helpless when faced with this profile, lacking an equivalent mechanism to secure the deduction of monthly installments.
4.3. No formal credit history
An informal profile has, most of the time, never borrowed from a bank: there is therefore no repayment history to consult, yet this history is a key element of risk analysis. This statistical gap reinforces the caution — often excessive given the actual risk — of formal institutions towards these profiles, who find themselves penalized not because they repay poorly, but because they are invisible to the eyes of classic evaluation tools.
4.4. No real guarantees
Lacking titled real estate or a bank account with predictable movement, informal profiles generally cannot offer alternative guarantees (mortgage, pledge, joint guarantee from a salaried third party) that banks require to compensate for the absence of domiciliation.
4.5. The cost and slowness of processing, for often modest amounts
The financing needs of the informal sector are frequently small and short-term (restocking, advancing an input, dealing with an emergency), which makes the processing of a classic bank application — with its delays and fixed processing fees — disproportionate to the service provided. It is precisely this imbalance between the cost of processing an application and the size of the need that historically justified the growth, alongside banks, of a dedicated microfinance sector: in Benin, several hundred microfinance institutions (MFIs) and decentralized financial systems (SFDs) — mutuals, savings and credit cooperatives, direct credit institutions — now cover a significant portion of the active population, with group solidarity guarantee mechanisms replacing mortgage or salary-based guarantees.
5. Alternatives being developed for this audience
- Microfinance institutions (MFIs/SFDs): they remain the main point of contact between informal profiles and formal credit, with smaller amounts, shorter durations, and guarantees based on group solidarity rather than salary domiciliation.
- Targeted public programs: schemes such as the microcredit lines managed by the National Microfinance Fund explicitly target income-generating activities in the informal sector, with disbursement and repayment directly via mobile phone, without having to visit a branch.
- Mobile money-backed nano-credit: small amounts, disbursed in a few clicks based on the applicant's mobile money transaction history, repaid over very short cycles — a response directly calibrated to the occasional cash flow needs of traders and artisans.
- Alternative credit scoring: several technological solutions like Visacredit Tech deployed in the sub-region now allow lenders to use non-traditional data — mobile money transaction history, phone recharge behavior, participation in rotating savings groups, activity in cooperatives — to build a credit score where no pay slip exists. This approach does not replace classic banking documents: it builds a functional equivalent of income proof and repayment history, based on data that informal profiles actually generate in their daily activities.
- Bankability coaching: before the loan, support, offered by Visacredit Tech, towards formalization (keeping a simplified accounts book, regularity of deposits into a mobile money or savings account, progressive formalization of the activity) allows some informal business owners to move closer, over time, to the standards expected by traditional lenders.
6. Points of vigilance, regardless of profile
- Compare the APR rather than just the advertised nominal rate, which does not reflect application fees or insurance premiums;
- Check the assignable portion actually available before accumulating several loans, at the risk of application rejection or over-indebtedness;
- Carefully read the irrevocability clauses of the domiciliation, which bind the employee to their lending bank for the entire duration of the loan;
- For an informal profile applying to an MFI or a nano-credit scheme, check the effective rate actually charged: the legal ceiling applicable to microfinance institutions is higher than that of banks, which can make some products significantly more expensive than a classic bank loan, for the same amount.
Conclusion
Consumer credit in Benin remains, in its current architecture, tailored to a specific profile: the formal employee, with a permanent contract, whose income can be domiciled and verified month after month. It is this very mechanism of irrevocable salary domiciliation that secures the bank and speeds up the processing of the application — and it is its absence that explains, more than any other factor, why the actors of the informal economy, who are the majority in Beninese economic activity, remain on the margins of classic bank credit. Responses to this imbalance already exist — microfinance, mobile nano-credit, alternative scoring based on non-traditional data, bankability coaching — but they will remain only partial correctives as long as they are not better articulated with traditional banking channels, to allow an informal income, regular but not salaried, to become just as "legible" to a lender as a pay slip.
comment
No comments
Leave a comment