

Real estate loans in Ivory Coast: how to finance the purchase of a property that is already built?
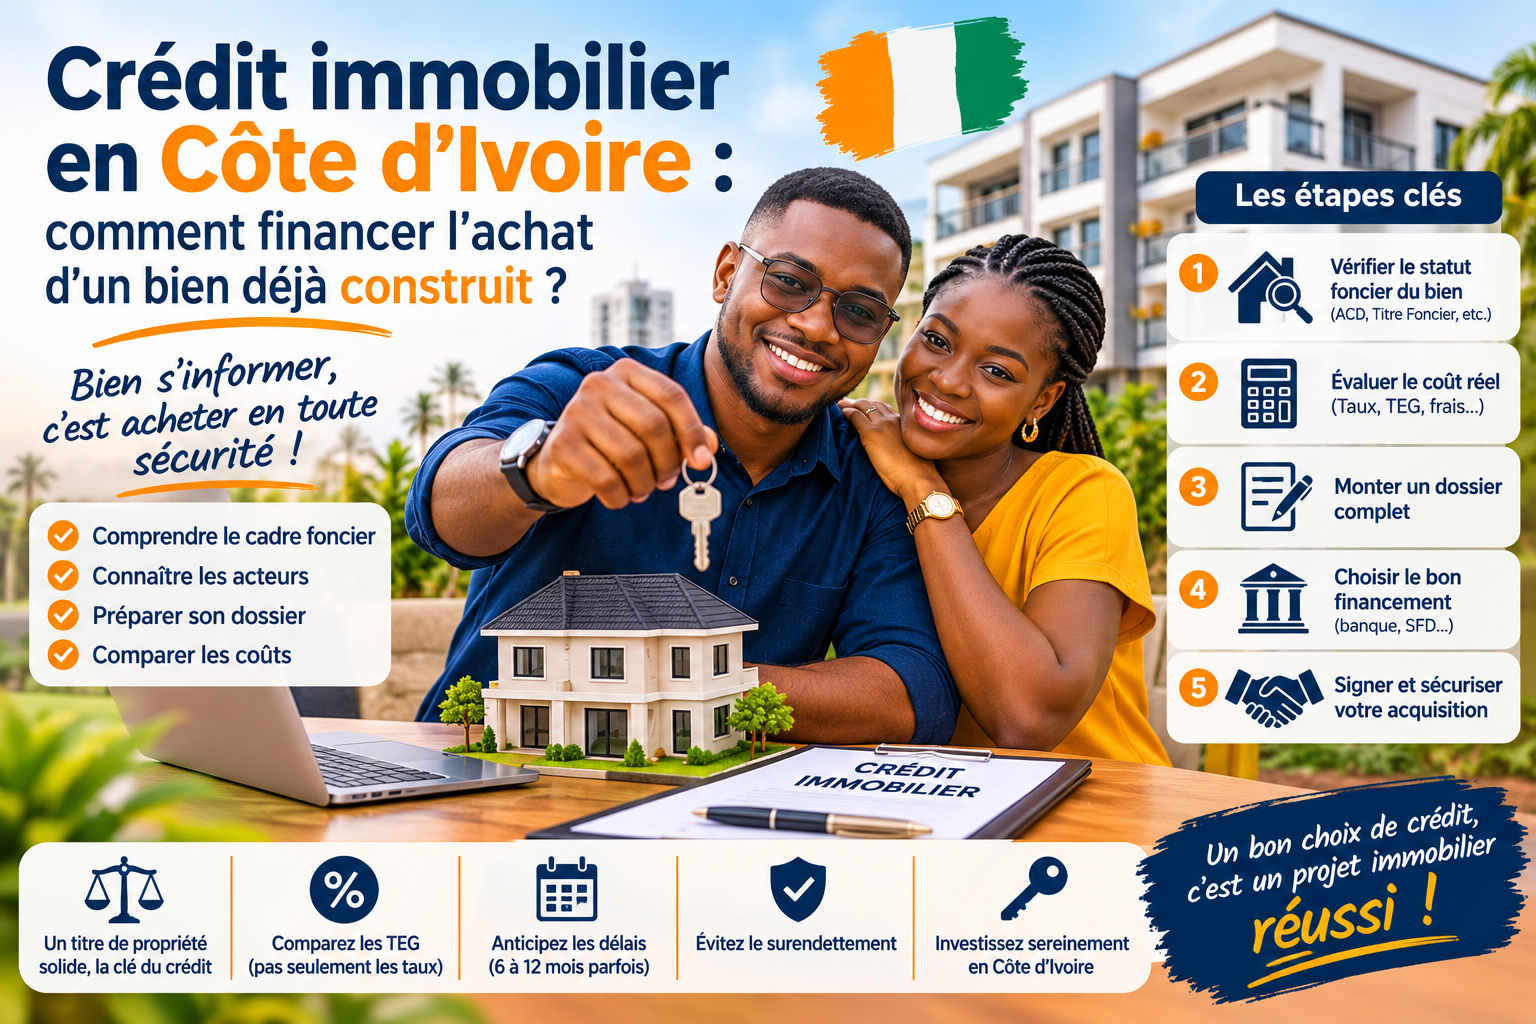
Mortgage credit in Côte d'Ivoire: how to finance the purchase of an already built property
Acquiring an already built house or apartment is, for many Ivorian households, a major step in building wealth, often faster and less risky than building from plans. But two points determine the outcome of the financing: the solidity of the property title and the real cost of the credit. This article presents the land framework resulting from recent reforms, the financing players, the process of an application, the documents to gather, and the points of vigilance. It then addresses, with their risks, the possible solutions when the definitive title is not yet available.
1. Why buying an already built property is attractive
Unlike a construction loan, which finances an uncertain operation, buying a finished property offers the lender a central advantage: the property exists, it can be visited, measured, and assessed immediately. For the buyer, this also means a more readable timeline, since there are no construction hazards or budget overruns to fear.
Urban pressure around Abidjan and its peri-urban communes (Bingerville, Anyama, Songon) has also made real estate one of the preferred investments of Ivorian households and investors. This is one more reason to secure every stage of the acquisition.
2. The land framework: understanding the documents before signing
The Ivorian land regime distinguishes between urban and rural areas. The reforms undertaken between 2023 and 2025 have above all strengthened the traceability of urban land from subdivisions.
In urban areas
- The Definitive Concession Order (ACD) is the act by which the State confers definitive ownership of urban land from an approved subdivision. It is issued by the Ministry of Construction, Housing and Urban Planning (MCLU), according to the procedure set by Decree No. 2021-785 of December 8, 2021.
- The Land Title is established with the Conservation of Land Property and Mortgages (CPFH). It makes the right enforceable against third parties. The ACD and the Land Title are closely linked, but they are not strictly the same document: ask your bank which one it requires to constitute the mortgage.
- The Customary Right of Use Certificate (ADU) replaces the former village certificate in the procedure for obtaining the ACD. It is secured by a QR code and a unique identifier. Its timeline is as follows: introduced by a communication in the Council of Ministers in 2023, it came into application in July 2024 for new subdivisions, then became mandatory for any ACD application in the first half of 2025, after a delay of a few months compared to the initially announced date of January 1, 2025.
- The former village certificate does not make its holder the legal owner of the land. It is not, however, devoid of effect: its holders are invited to file an ACD application, provided they are mentioned in the village guide. Buying on the sole basis of a village certificate therefore remains a risk, but regularization is possible.
In rural areas
The Land Certificate, issued by the Department Prefect after an official land inquiry, secures customary rights over rural land, before a possible transformation into a land title.
Timelines to integrate into your financing plan
The ACD procedure provides for an official deadline, but the deadlines observed in practice are generally longer: count several months, often 6 to 12 months, and more if the file is incomplete or disputed. An additional verification tool exists with the Unique Land Identifier of Côte d'Ivoire (IDUFCI), intended to trace the documentary history of a plot independently of the seller's declarations. Check with the MCLU the consultation procedures in force.
3. Who finances the purchase of a property?
- Commercial banks offer mortgage loans guaranteed by a mortgage. They almost systematically require a definitive title (ACD or Land Title), because it is this that allows the first-rank mortgage to be registered.
- Decentralized financial systems (SFDs) finance housing projects with often different guarantee requirements. They may suit profiles whose title is not finalized or whose income is not very formalized, but their rates are generally higher (see the usury ceiling below).
- Public and institutional housing support schemes (support funds, regional mortgage refinancing, housing programs) can facilitate access to credit. Ask your bank about the programs available to your profile.
4. The process of a mortgage application
Step 1: verify the exact land status of the property
Establish whether the property is covered by an ACD or a definitive Land Title, or only by an intermediate document (ADU, allocation letter, former village certificate). Rely on the IDUFCI of the plot and on a land status report (MCLU) or a land registry status (CPFH) depending on whether the Land Title already exists or not. These statuses confirm the absence of dispute, mortgage, or seizure.
Step 2: have the property appraisal carried out
The expert estimates the market value of the property by combining the value of the land and the reconstruction cost of the buildings, depreciated according to their age and maintenance. This report serves as the basis for the bank to calibrate the loan amount.
Step 3: sign the sales promise before a notary
It identifies the property, sets the price, and lists the suspensive conditions (tax clearance, release of any mortgages, vacating of premises, obtaining the loan). The bank often processes the application on this basis.
Step 4: regularize the title if necessary
If the property is covered only by an ADU or an allocation letter, the ACD application often falls to the buyer after the transaction. The bank then generally conditions the disbursement of the credit, at least in part, on the effective obtaining of the title. Therefore, plan for this delay in your schedule.
5. Documents to gather
| Document | Role in the file |
|---|---|
| ACD or Land Title (urban area) / Land Certificate (rural area) | Proof of definitive ownership, condition for mortgage credit |
| ADU | Entry point for the ACD application if the definitive title is not yet established |
| IDUFCI of the plot | Verification of the documentary history of the land |
| Land status report (MCLU) or land registry status (CPFH) | Confirmation of the absence of dispute, mortgage, or seizure |
| Real estate appraisal report | Valuation basis for the loan |
| Notarized sales promise | Contractual commitment between parties |
| Proof of income, identity, and address | Assessment of repayment capacity |
6. How much does the credit really cost?
Duration and rate
A mortgage loan most often extends over 10 to 20 years, sometimes more depending on the institution. Rates vary according to the bank, the borrower's profile, and the level of contribution: always ask for a written simulation. As a general benchmark, the average borrower rate of WAEMU banks was 6.67 % in May 2026 according to the BCEAO. It covers all types of credit, so it does not constitute a mortgage rate.
The legal ceiling (usury rate)
Since June 1, 2026, it has been set at 14 % per year for banks and 24 % per year for credit financial institutions, microfinance institutions, and other economic agents (BCEAO Opinion No. 007-12-2025). This ceiling applies to the Effective Annual Rate (APR), that is, the total cost of the credit (interest, application fees, compulsory insurance, etc.) and not to the nominal rate alone.
A numerical example (illustrative)
To borrow 20 million CFA francs at 9 % per year, excluding insurance and fees:
| Duration | Approximate monthly payment | Approximate total interest |
|---|---|---|
| 10 years | 253,000 CFA francs | 10.4 million CFA francs |
| 15 years | 203,000 CFA francs | 16.5 million CFA francs |
Extending the duration from 10 to 15 years lightens the monthly payment by about 50,000 CFA francs, but adds about 6 million CFA francs in interest. This is the real trade-off of any mortgage loan: affordable monthly payment or minimal total cost.
Other costs to budget for
- the personal contribution, which banks generally require for part of the price;
- death-disability insurance, often requested by the lender;
- notary, registration, and transfer fees;
- appraisal and application fees.
Lenders also examine the debt ratio: the share of your income devoted to all monthly payments must not exceed the threshold set by the institution.
7. When the definitive title is not yet available: alternatives and their risks
Many buyers or future builders do not yet have an ACD or a Land Title. Several paths exist, but none is without counterpart.
Regularize first, finance later
This is the safest option: obtaining the ACD (or accelerating the conversion of an old provisional act, depending on the situation of the property) opens access to classic mortgage credit and to the building permit. Check with the MCLU on the procedure applicable to your file.
Construction credit with progressive disbursements
It finances a construction site in stages: you borrow, and pay interest, only on the sums already disbursed. This is a real advantage compared to capital fully paid from the first day. It generally requires a secured land title and a building permit.
Staged financing with an SFD or through successive credits
Some households build gradually by chaining short loans. The economic interest is simple: by borrowing only what one spends, one reduces the average outstanding capital. But this arrangement carries significant risks:
- the APR of these loans is often higher, within the limits of usury ceilings: 14 % for banks, 24 % for other lenders;
- the monthly payments are heavier, because the duration is short, and each loan must be repaid with your income;
- there is no mortgage guarantee on land without a definitive title;
- a repayment incident can interrupt the construction site and leave a construction unfinished;
- without a secured title, the building permit is difficult to obtain, and building without authorization exposes to administrative risks and resale difficulties;
- consumer loans are designed for consumer needs: their use for a real estate project requires carefully verifying your repayment capacity to avoid over-indebtedness.
This arrangement can prove less costly than borrowing the entire capital over 15 to 20 years, but only if your income easily absorbs higher monthly payments and if the land is secured. Seek advice from your bank or SFD and compare APRs on the same basis before committing.
8. Points of vigilance for the buyer
- Never pay money on the sole faith of an unregularized village certificate: verify the ADU or the title, and the status of the subdivision.
- Verify the IDUFCI of the plot and the land status or land registry status before any payment, regardless of the seller's declarations.
- Systematically request the Land Title or ACD number and have it confirmed with the competent administration (CPFH or MCLU).
- Integrate the real regularization timelines into your financing plan.
- Compare APRs, not just nominal rates, and request the amortization schedule.
- Have the sales promise reviewed by a notary before signing.
- Keep proof of each payment and require a receipt.
9. Frequently asked questions
Can I obtain a bank mortgage loan with an ADU alone?
In principle no: banks require a definitive title for the mortgage. The ADU is the entry point for the ACD application. Some banks may, however, disburse the credit in stages, conditional on obtaining the title.
My seller has an old village certificate. Should I give up the purchase?
Not necessarily, but the operation is risky. You must verify that the seller appears in the village guide, initiate the regularization, and plan for the corresponding timelines and costs in the price and schedule.
What does the usury ceiling mean for me?
No credit can have an APR higher than 14 % (banks) or 24 % (other lenders). If the APR proposed to you exceeds this ceiling, it is irregular.
Should I favor a long or short duration?
A short duration costs less in total but imposes a heavier monthly payment. The right choice is the shortest duration that your budget comfortably supports.
Conclusion
Financing a property in Côte d'Ivoire is part of a land reform context that aims to secure transactions and reduce multiple sales: generalization of the ADU, digitalization of procedures, unique identifier of plots. For the buyer, documentary vigilance remains essential, because the real regularization timelines often exceed the official deadlines. More broadly, the cost of a project is judged on the APR, the duration, and the security of the title, and not only on the advertised rate.
This article is provided for information purposes and does not replace the advice of a notary or your financial institution. Land rules and rates evolve: verify them with the relevant administrations and lenders before any commitment.
Further reading (sources to consult)
- BCEAO, Opinion No. 007-12-2025 of December 31, 2025 on the usury rate in the WAEMU
- Ministry of Construction, Housing and Urban Planning (MCLU): ACD and ADU procedures
- Decree No. 2021-785 of December 8, 2021 determining the procedure for issuing the ACD
- BCEAO, surveys on banking conditions in the WAEMU
comment
No comments
Leave a comment