

Consumer credit in Ivory Coast: required documents, operation and access for the informal sector?
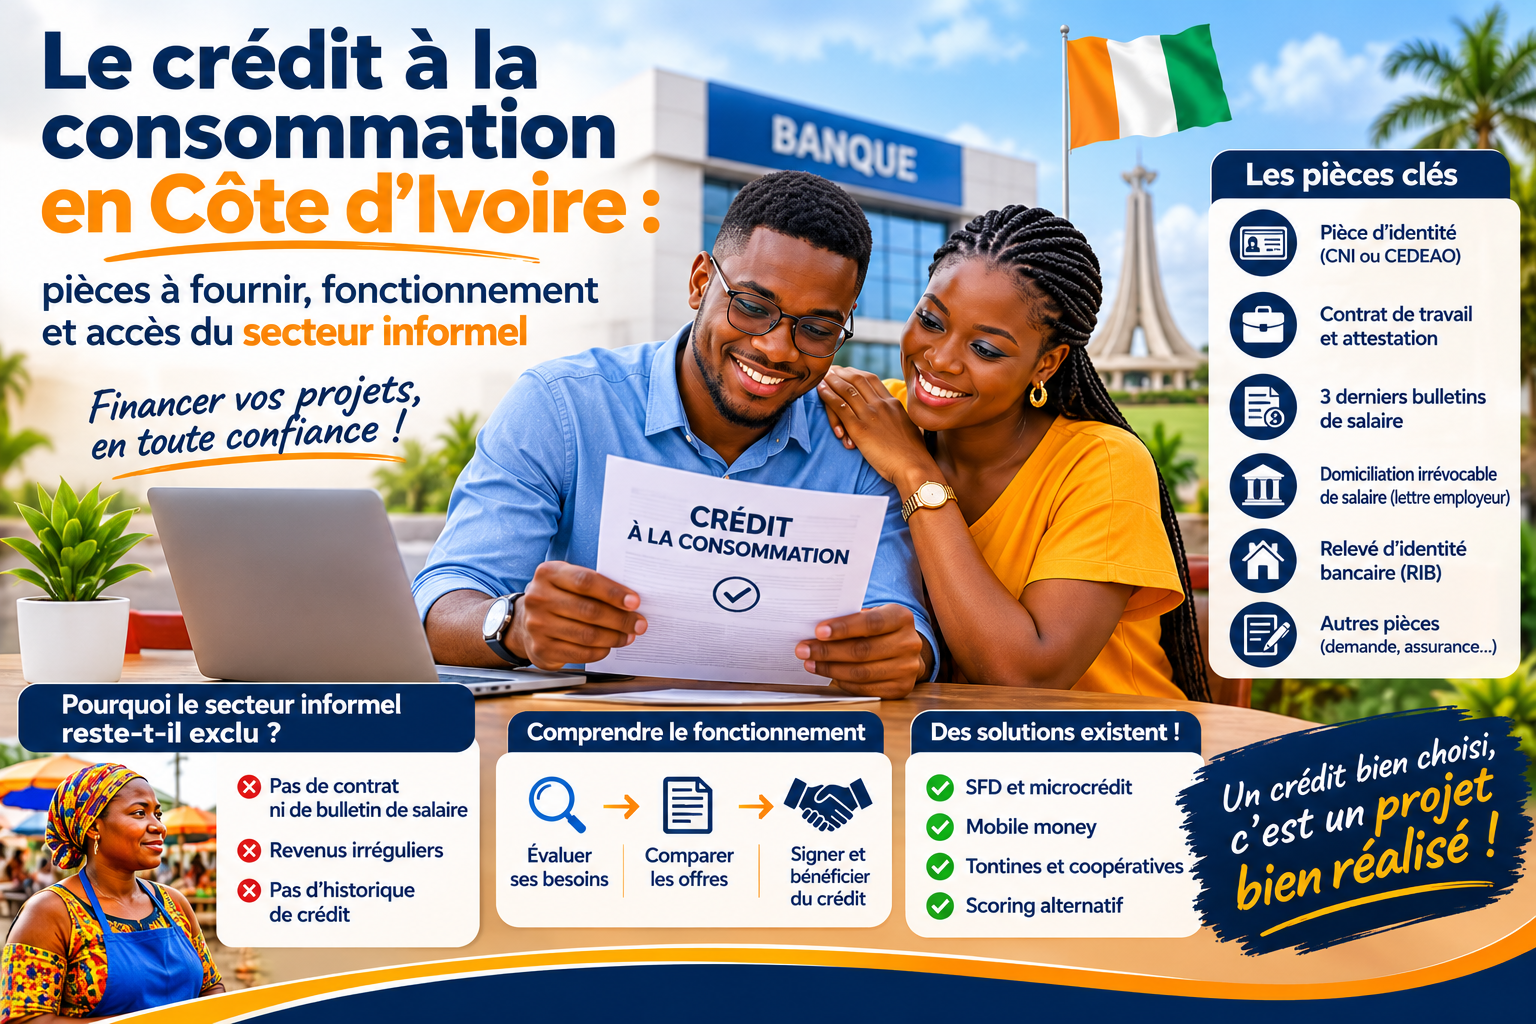
Consumer credit in Côte d'Ivoire: documents required, how it works, and access for the informal sector
Consumer credit is one of the most sought-after products in Ivorian banks: it finances the purchase of equipment, a family event, or a temporary cash need. Unlike mortgage credit, it requires neither a mortgage nor a land title, which in theory makes it more accessible. But it remains built around a specific profile: the formal-sector employee, under contract, whose income is verifiable and can be domiciled. This article details the typical process of a consumer credit application, explains its real cost, then analyzes why this same process remains difficult to access for informal economy workers and what solutions exist.
1. What is consumer credit?
Consumer credit is a short- or medium-term loan, either unallocated or allocated to a specific use. It differs from mortgage credit by the absence of a mortgage guarantee and by significantly shorter terms. It relies above all on the borrower's regular repayment capacity, generally demonstrated by a domiciled salary.
This product is designed for consumer needs. Using it to finance a real estate project or construction requires particular vigilance: the monthly payments are heavier than those of a mortgage loan and no guarantee on the property protects the borrower.
2. The standard application: documents required from a formal-sector employee
The lists below correspond to the most common practices. Each bank sets its own requirements: ask your institution for its list before gathering the documents.
2.1. Identity and personal situation
- Valid identity document: Ivorian national identity card or CEDEAO card;
- Client confidential information form: civil status, family situation, address, assets, and existing financial charges;
- Bank account details (RIB).
2.2. Employment and income proof
- Employment contract (a permanent contract is often required);
- Certificate of employment issued by the employer;
- Recent pay slips, generally the last three.
2.3. Irrevocable salary domiciliation
This is the central piece of the arrangement. It is a commitment, signed by the employer and the employee, to pay all remuneration into the account opened with the lending bank. It allows the bank to deduct the monthly payment at source and constitutes the main guarantee of the credit. Depending on the institution, civil servants may have to provide a certificate of non-revocation of the domiciliation, while private-sector employees sign an irrevocable domiciliation commitment with their employer.
2.4. Other frequently requested documents
- Credit application and acknowledgment of debt;
- Death-disability insurance membership form;
- Certificate of non-indebtedness (depending on the bank);
- Passport photos.
2.5. Summary of documents
| Category | Documents |
|---|---|
| Identity | Valid Ivorian national identity card or CEDEAO card |
| Personal situation | Confidential information form (civil status, charges, assets) |
| Employment | Employment contract, certificate of employment from employer |
| Income | Last three pay slips |
| Guarantee | Irrevocable salary domiciliation (employer letter, employee commitment) |
| Bank account | Bank account details (RIB) |
| Insurance and commitment | Death-disability insurance form, acknowledgment of debt |
3. Approval conditions and the real cost of credit
3.1. What weighs in the decision
- The assignable portion is the share of remuneration that can be allocated to loan repayment. It is governed by Decree No. 2014-370 on the regime of the assignable portion and the seizable portion and calculated in income brackets. In practice, banks ensure that all monthly payments remain around one third of net salary, all loans combined. Have the exact calculation confirmed by your bank.
- Contractual status: a permanent contract is often required, as well as a certain seniority.
- Duration: it varies according to the institution and the amounts, most often from one to five years.
- The effective annual rate (APR), the only indicator reflecting the true cost of credit.
3.2. The legal ceiling (usury rate)
Since June 1, 2026, the usury rate has been set at 14 % per year for banks and 24 % per year for credit financial institutions, microfinance institutions, and other economic agents (BCEAO Opinion No. 007-12-2025). It applies to the APR, that is, the total cost of the credit: interest, application fees, compulsory insurance, and other fees. An APR above this ceiling is irregular.
3.3. A numerical example (illustrative)
For a loan of 3 million CFA francs at 10 % per year over 36 months, excluding application fees and insurance:
| Element | Approximate amount |
|---|---|
| Monthly payment | 96,800 CFA francs |
| Total interest | 485,000 CFA francs |
| Minimum net salary to respect a one-third ratio | 290,000 CFA francs |
Application fees and death-disability insurance are added to these figures and push the APR above the nominal rate. Always ask for the written credit offer with the APR and the amortization schedule.
4. Why the informal sector remains largely excluded
4.1. The observation: a country very « included » in the broad sense, little banked in the strict sense
Two BCEAO indicators must be distinguished. The broad financial inclusion rate, which takes electronic money (mobile money) into account, stood at 82.2 % in Côte d'Ivoire in 2021, a high level for the WAEMU, slightly behind Togo (85.7 %) and Benin (85.5 %). Strict bank penetration, that is, holding a bank account, remains much lower: about 26 % in 2021 and 29.5 % in 2022, with an estimate around 31 % cited in 2025. In other words, many Ivorians already use financial services, particularly mobile money, but few access classic bank credit. It is this gap that explains the difficulty of informal workers in obtaining consumer credit.
4.2. No employment contract or pay slip
Without a formal employer, there is no employment contract, no certificate of employment, and no regular pay slip: the foundation on which a bank assesses income stability.
4.3. The impossibility of domiciling a salary that does not exist
The central guarantee of classic consumer credit, irrevocable salary domiciliation, has no direct equivalent for self-employed income, which is irregular and spread across multiple channels (cash, mobile money, credit sales).
4.4. No credit history and no real guarantees
An informal worker has, most of the time, never borrowed from a bank and generally cannot offer the alternative guarantees that institutions require in the absence of salary domiciliation.
4.5. The authorities' efforts
The General Directorate of the Treasury and Public Accounting conducts a national awareness campaign each year on bank penetration, insurance, and financial inclusion. The 2026 edition was launched on August 13, 2026, in Abidjan and ran from August 16 to September 5 in three regions: Kabadougou, N'Zi, and Sud-Comoé. It aims to bring banking services, insurance products, and microfinance closer to households, agricultural cooperatives, and very small businesses. It is part of the BCEAO's 2025-2030 regional financial inclusion strategy. This is an awareness-raising action, not a new credit product: it does not, by itself, change banks' lending criteria.
5. Alternatives being developed for this audience
- Decentralized financial systems (SFDs) finance local projects for self-employed individuals and small traders, often through group solidarity guarantee mechanisms or prior savings. Their rates are generally higher than those of banks, with a legal ceiling of 24 %.
- Mobile money-linked microcredit offers are developing. They assess the client based on their transaction history. Verify that the issuer is approved, and compare the total cost rather than just the advertised commission.
- Tontines and cooperatives already provide a form of local credit and savings. Regular participation can constitute proof of financial reliability when applying for credit.
- Alternative credit scoring uses non-traditional data (mobile money history, payment regularity, cooperative activity) to estimate repayment capacity where no pay slip exists. This is a promising path, but it requires the client's consent, the protection of their personal data, and transparency on the criteria used.
6. Building a file as an informal worker
In the absence of pay slips, institutions willing to study a self-employed application more often request elements such as:
- mobile money or account statements over several months, showing regular receipts;
- proof of activity: trader's card, registration in the trade register (RCCM), tax identification number, or certificate from a professional association, cooperative, or market;
- an identity document and proof of address;
- savings history or participation in a tontine;
- a guarantor or joint guarantee, depending on the institution.
These documents do not guarantee the granting of credit, but they improve the readability of the file. Opening an account and channeling your income through it for several months is often the first useful step.
7. Points of vigilance, regardless of profile
- Compare the APR rather than just the advertised nominal rate.
- Check the assignable portion actually available before accumulating several loans.
- Carefully read the irrevocability clauses of the domiciliation and the exit conditions.
- With an SFD, check the effective rate actually charged: the legal ceiling (24 %) is higher than that of banks (14 %).
- Verify that the lender is approved, and be wary of any request for payment before the disbursement of funds.
- Avoid chaining several loans to finance the same project without having calculated the total of your monthly payments.
8. Frequently asked questions
Can I obtain consumer credit without a domiciled salary?
This is very rare with banks, because domiciliation is their main guarantee. SFDs and some lenders offer other mechanisms, with different conditions and rates.
Is the assignable portion the same for everyone?
No. It is calculated in income brackets and depends on your existing loans.
What is the difference between the nominal rate and the APR?
The nominal rate is only used to calculate interest. The APR adds application fees, insurance, and other fees: it is the APR that is capped by the usury rate.
Can I use consumer credit to build my house?
Technically, it is possible, but it is risky: high monthly payments, short durations, no guarantee on the property, and risk of an unfinished construction site in case of payment difficulty. Compare with a mortgage loan or a construction loan.
Conclusion
In its classic banking architecture, consumer credit remains tailored to the formal employee with a stable contract and salary domiciliation. Informal workers, although numerous in using mobile money and microfinance, encounter a gap between their actual use of financial services and the criteria of traditional banks. Awareness campaigns, microfinance, and evaluation tools based on alternative data open bridges, provided one remains vigilant about the cost of credit and the approved status of the lender.
This article is provided for information purposes and does not constitute financial advice or a credit offer. Approval conditions vary by institution, and rates and rules evolve: verify them with your bank or microfinance institution before any commitment.
Further reading (sources to consult)
- BCEAO, Opinion No. 007-12-2025 of December 31, 2025 on the usury rate in the WAEMU
- BCEAO, reports and dashboards on financial inclusion in the WAEMU
- Decree No. 2014-370 on the regime of the assignable portion and the seizable portion
- General Directorate of the Treasury and Public Accounting: national campaign for bank penetration and financial inclusion 2026
- BCEAO's 2025-2030 regional financial inclusion strategy
comment
No comments
Leave a comment